Skip to content
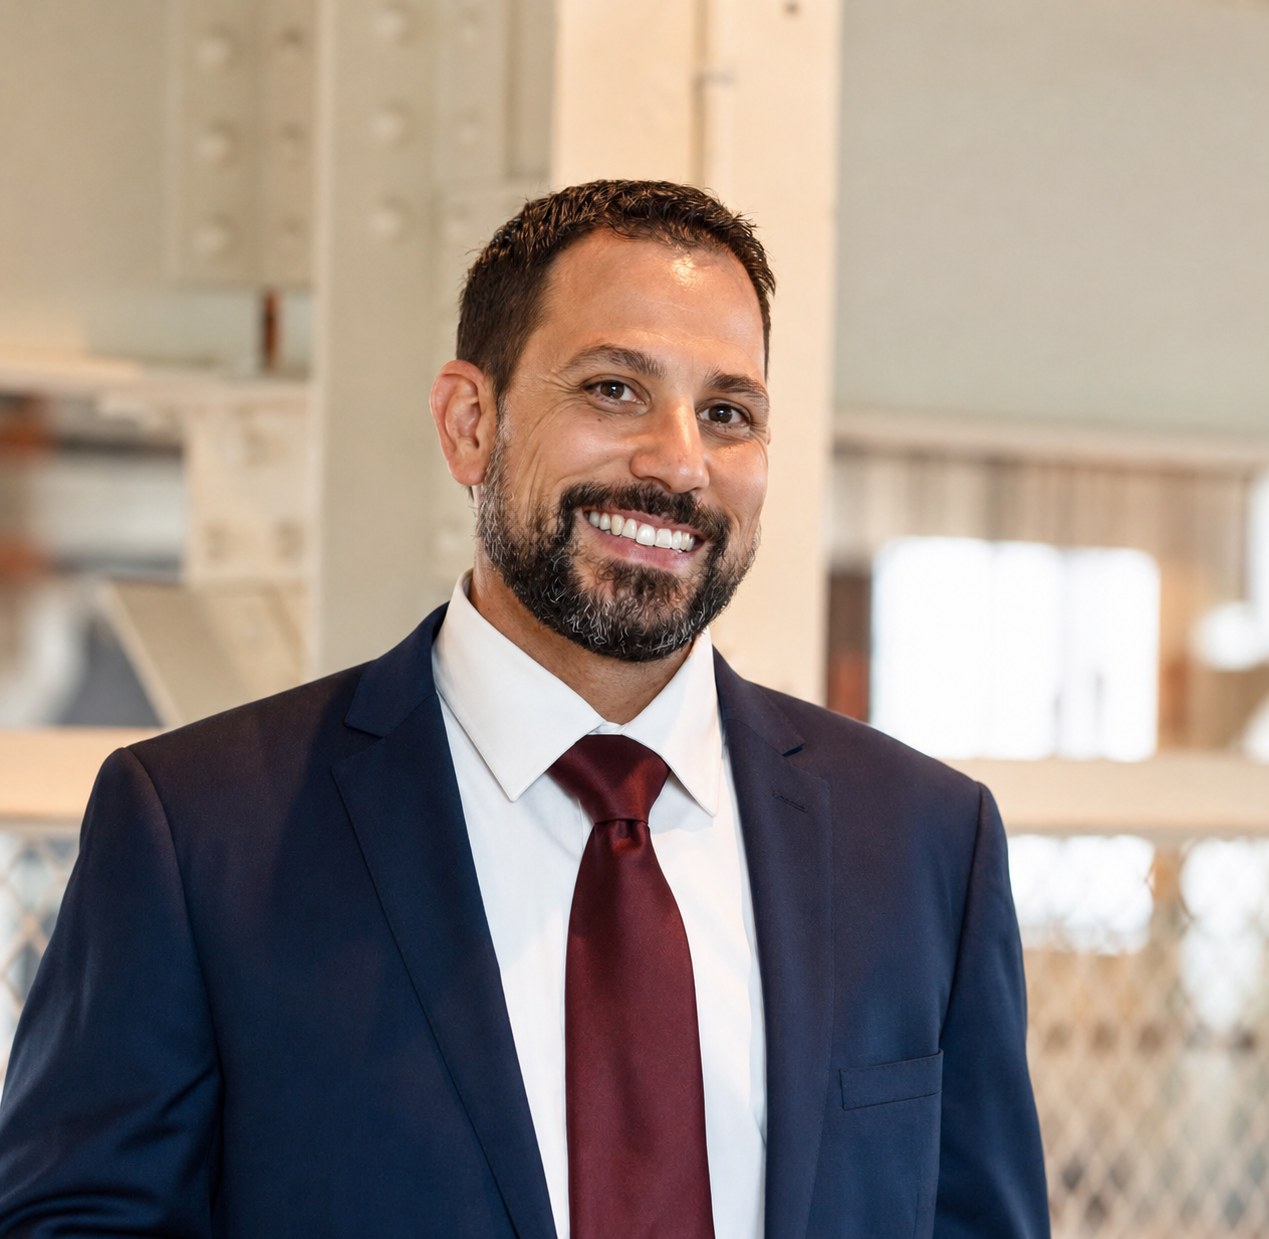
Photo of Nate Corrieri

About Nate Corrieri

I'm Nate Corrieri, and I help mid-career professionals, salespeople, and small-business owners make informed decisions about life insurance. My focus is on finding coverage that fits your income, your obligations, and your longer-term financial picture.

I work with multiple carriers, so I can show you a range of options and explain the real differences between term, permanent, and specialty policies. No single product is right for everyone, and my job is to help you understand what you're buying before you commit.

Most of my clients come to me because they want straight answers. We'll talk through your situation, compare options side by side, and you'll leave with a clear sense of what makes sense and what doesn't.

How I work

My approach with clients

I focus on showing you the full picture. That means walking through term, universal, and whole life options side by side, explaining where each one makes sense and where it doesn't. Most people don't need the most expensive policy, and some don't need the cheapest one either. My job is to make sure you understand what you're paying for.

I work with clients who want to ask questions and think things through. You'll get straight answers about premiums, underwriting, cash value, and how different products actually work. If something doesn't make sense for your situation, I'll tell you.

Once you decide, I handle the application and stay in touch through underwriting. You won't be handed off or left guessing about next steps.

Where I go deep

What I help clients navigate

Life Insurance

Term, Universal, and Whole Life: What You're Actually Buying

Term life gives you a large death benefit for a set number of years at a low premium, but it expires. Universal life offers flexible premiums and a cash value account, but requires active management to avoid lapse. Whole life costs more and builds guaranteed cash value, covering you for life. Each has a place depending on your timeline, budget, and whether you want the policy to do more than just pay a death benefit.

  • Term Life
  • Whole Life
  • Universal Life
  • Survivorship / Second-to-Die Life
  • Children's Life Insurance
  • Simplified-Issue Life

Mortgage Protection

Matching Coverage to Your Loan Structure

Mortgage protection can be level term (death benefit stays the same), decreasing term (benefit drops as your loan balance falls), or permanent (covers you beyond the mortgage payoff). Return-of-premium term refunds your premiums if you outlive the term, but costs significantly more. I'll show you the cost difference and help you decide if the refund feature is worth it based on your broader financial plan.

  • Term Life
  • Decreasing-Term Life
  • Permanent Life
  • Return-of-Premium Term
  • Living-Benefit Riders

Final Expense

Whole Life, Simplified-Issue, and Guaranteed-Issue Compared

Final expense whole life requires some health underwriting and offers the best rates if you qualify. Simplified-issue skips the exam but asks health questions, leading to moderate premiums. Guaranteed-issue accepts anyone but costs more, pays lower face amounts, and may limit full benefits in the first two years. I'll review your health situation and show you which option gives you the best combination of approval likelihood and cost.

  • Final Expense Whole Life
  • Simplified-Issue Final Expense
  • Guaranteed-Issue Final Expense
  • Burial Insurance

Situations I know well

Who I often help

  • Small Business Owners

Coverage options from carriers I work with

  • Corebridge Financial
  • Foresters Financial
  • Gerber Life
  • Mutual of Omaha
  • Liberty Bankers Life
  • Aetna Senior Supplemental
  • AIG
  • American-Amicable
  • Americo
  • MassMutual
  • Principal Life
  • Royal Neighbors of America

Verify me

Licensing & identity

Every number here is public record. Look it up before we ever speak.

Nate Corrieri

Licensed insurance producer

State license numbers

  • TX · #376035130

Carriers include Corebridge Financial, Foresters Financial, Gerber Life, Mutual of Omaha, Liberty Bankers Life, Aetna Senior Supplemental, AIG, American-Amicable, Americo, MassMutual, Principal Life, Royal Neighbors of America.

License information can be verified through your state's department of insurance.

Nate Corrieri is a licensed insurance producer.

State insurance licenses: TX #1923818.

Insurance products and their features, availability, and benefits vary by state and by insurance carrier. This website provides general information only; it is not an offer of coverage, and all policy terms, conditions, and exclusions are controlled by the issued policy.

Quotes and coverage are subject to underwriting, eligibility, and approval requirements.

Straight answers

Common questions

What's the real difference between term and whole life insurance?

Term covers you for a set number of years (usually 10, 20, or 30) and costs less because it eventually expires. Whole life covers you for life and builds cash value, but premiums are significantly higher. Term makes sense if you need a lot of coverage during working years. Whole life works if you want lifelong protection and are comfortable with the cost.

How much life insurance do I actually need?

A good starting point is 10 to 12 times your annual income, adjusted for debts like your mortgage, future education costs, and how long your family would need income replacement. We'll walk through your specific numbers so the coverage amount reflects your actual obligations, not a generic formula.

Can I get mortgage protection if I refinanced or bought recently?

Yes. Mortgage protection is just life insurance structured around your loan balance and term. It doesn't matter when you bought or refinanced. We'll look at your current mortgage details and match the coverage period and amount to what you actually owe.

What does simplified-issue and guaranteed-issue mean for final expense?

Simplified-issue asks a few health questions but skips the medical exam. Guaranteed-issue accepts everyone regardless of health, though coverage may be limited in the first two years. Guaranteed-issue costs more and offers lower face amounts, but it's an option if you've been declined elsewhere.

Does universal life really let me adjust my premiums and death benefit?

Within limits, yes. Universal life has flexible premiums and a death benefit you can increase or decrease (subject to underwriting). That flexibility comes with complexity. The policy's cash value must stay high enough to cover internal costs, or the policy can lapse. I'll show you how the mechanics work before you decide if that flexibility is worth it.

If I have a mortgage, do I need separate mortgage protection or is regular term life enough?

Regular term life can absolutely cover your mortgage. Mortgage protection is just term life sized and structured around the loan. The main difference is whether you want a decreasing benefit that tracks your loan balance (sometimes cheaper) or level term that covers the mortgage plus other needs. We'll compare both and you can decide what fits.

Let's find the right coverage

Start with a quick conversation. No pressure, no obligation.

Call Get Your Free Quote