Skip to content

Life Insurance That Actually Works for Your Financial Plan

Clear options. Honest guidance. Coverage built around the people and priorities that matter most to you.

Hero image for Trust Life of Texas

Coverage options from carriers I work with

  • Corebridge Financial
  • Foresters Financial
  • Gerber Life
  • Mutual of Omaha
  • Liberty Bankers Life
  • Aetna Senior Supplemental
  • AIG
  • American-Amicable
  • Americo
  • MassMutual
  • Principal Life
  • Royal Neighbors of America

Coverage I can help with

Life Insurance

Life insurance replaces your income if something happens to you, protecting the people who depend on your paycheck. I help you compare term policies (lower cost, set period) and permanent options (lifelong coverage, cash value component) so you can choose based on your budget and how long you need protection.

  • Term and permanent options from multiple carriers
  • Coverage amounts tied to your actual income and debts
  • Plain explanations of cost vs. benefit tradeoffs
What this covers

Term Life

Coverage for a set number of years. Usually the most affordable way to cover the stretch when a mortgage, an income, or kids at home still depend on you.

Level Term

The premium and the benefit both stay the same for the whole term. The most common shape, and the easiest to budget around.

Convertible Term

Includes the right to convert to permanent coverage later without new medical underwriting, within the policy conversion window.

Renewable Term

Can be renewed at the end of the term without new underwriting. The premium goes up based on your age at renewal.

Return-of-Premium Term

Pays back the premiums you paid if you outlive the term. Costs more up front than standard term for the same benefit.

Whole Life

Permanent coverage with a level premium and cash value that builds on a guaranteed schedule.

Universal Life

Permanent coverage with flexible premiums and an adjustable death benefit, so the policy can flex as circumstances change.

Indexed Universal Life (IUL)

Cash value is credited based on the movement of a market index, subject to a floor and a cap. The money is not invested directly in the market.

Guaranteed Universal Life (GUL)

Universal life structured around a guaranteed death benefit rather than cash value growth. Often the lower-cost route to lifetime coverage.

Survivorship / Second-to-Die Life

One policy covering two people that pays after the second death. Common in estate and legacy planning.

Children's Life Insurance

A small permanent policy on a child, usually including a guaranteed option to add coverage later regardless of their health then.

Simplified-Issue Life

Health questions instead of a medical exam. Faster to issue, generally with lower coverage limits.

Guaranteed-Issue Life

No health questions and no exam within the issue ages. Benefits are typically graded during the first policy years.

No-Medical-Exam Options

Underwritten from health questions and data rather than a paramedical exam. What qualifies depends on age, coverage amount, and carrier.

Key Person Life Insurance

Owned by a business on an employee whose loss would hurt it, so the business has cash to absorb the disruption.

Buy-Sell Funding

Funds a buy-sell agreement so surviving owners can buy out a departing owner's share without draining the business.

Executive Bonus Strategies

The business pays premiums on a policy the executive owns and keeps. Used as a retention benefit.

General information about how these work, not a recommendation. What is available to you depends on your situation, the carrier, and your state.

Who I work with

Small Business Owners
Get Your Free Quote
Life insurance

Mortgage Protection

Mortgage protection means your family can stay in the house if you're gone. I walk you through term policies that match your loan length, decreasing-term options that shrink as your balance drops, and permanent coverage if you want protection that outlasts the mortgage. We size it to your actual loan and talk through whether return-of-premium features are worth the extra cost.

  • Match coverage to your mortgage timeline and balance
  • Compare decreasing-term vs. level-term structures
  • Review return-of-premium options honestly
What this covers

Term Life

Term life sized to the mortgage balance and the years left on it.

Decreasing-Term Life

The benefit steps down over the term, roughly tracking a mortgage balance as it is paid off.

Permanent Life

Coverage that stays in force after the mortgage is gone, rather than ending with the term.

Return-of-Premium Term

Pays back premiums if you outlive the term. Higher cost than standard term for the same benefit.

Living-Benefit Riders

Riders that can advance part of the death benefit while you are living in qualifying situations such as terminal or chronic illness. Terms and availability vary by state and carrier.

General information about how these work, not a recommendation. What is available to you depends on your situation, the carrier, and your state.

Get Your Free Quote
Life insurance

Final Expense

I help families arrange small, simple policies that cover funeral and end-of-life costs.

What this covers

Final Expense Whole Life

A small permanent policy sized for funeral costs, burial, and the bills left behind.

Simplified-Issue Final Expense

Health questions, no medical exam. Typically issued in days rather than weeks.

Guaranteed-Issue Final Expense

No health questions. Acceptance is guaranteed within the issue ages, with a graded benefit in the first policy years.

Burial Insurance

Coverage intended specifically for funeral and burial expenses, paid to the beneficiary you name.

General information about how these work, not a recommendation. What is available to you depends on your situation, the carrier, and your state.

Get Your Free Quote
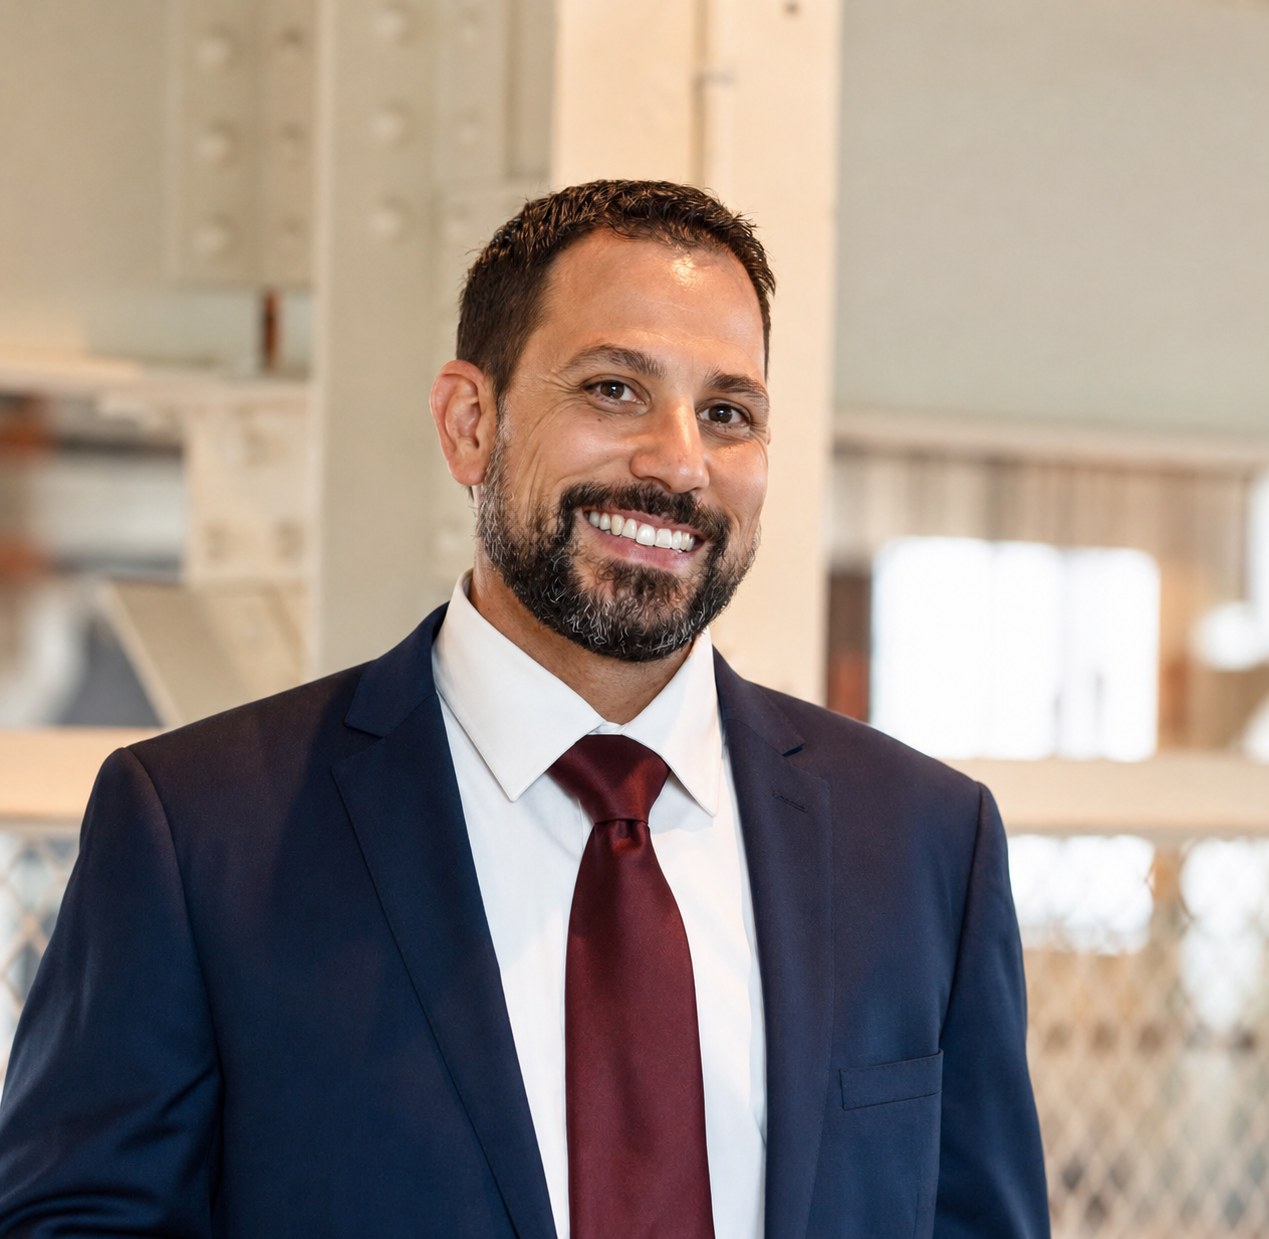
Photo of Nate Corrieri

Your agent

About Nate Corrieri

I'm Nate Corrieri, and I help mid-career professionals, salespeople, and small-business owners make informed decisions about life insurance. My focus is on finding coverage that fits your income, your obligations, and your longer-term financial picture.

I work with multiple carriers, so I can show you a range of options and explain the real differences between term, permanent, and specialty policies. No single product is right for everyone, and my job is to help you understand what you're buying before you commit.

Most of my clients come to me because they want straight answers. We'll talk through your situation, compare options side by side, and you'll leave with a clear sense of what makes sense and what doesn't.

More about Nate

Straight answers

Common questions

What's the real difference between term and whole life insurance?

Term covers you for a set number of years (usually 10, 20, or 30) and costs less because it eventually expires. Whole life covers you for life and builds cash value, but premiums are significantly higher. Term makes sense if you need a lot of coverage during working years. Whole life works if you want lifelong protection and are comfortable with the cost.

How much life insurance do I actually need?

A good starting point is 10 to 12 times your annual income, adjusted for debts like your mortgage, future education costs, and how long your family would need income replacement. We'll walk through your specific numbers so the coverage amount reflects your actual obligations, not a generic formula.

Can I get mortgage protection if I refinanced or bought recently?

Yes. Mortgage protection is just life insurance structured around your loan balance and term. It doesn't matter when you bought or refinanced. We'll look at your current mortgage details and match the coverage period and amount to what you actually owe.

What does simplified-issue and guaranteed-issue mean for final expense?

Simplified-issue asks a few health questions but skips the medical exam. Guaranteed-issue accepts everyone regardless of health, though coverage may be limited in the first two years. Guaranteed-issue costs more and offers lower face amounts, but it's an option if you've been declined elsewhere.

Does universal life really let me adjust my premiums and death benefit?

Within limits, yes. Universal life has flexible premiums and a death benefit you can increase or decrease (subject to underwriting). That flexibility comes with complexity. The policy's cash value must stay high enough to cover internal costs, or the policy can lapse. I'll show you how the mechanics work before you decide if that flexibility is worth it.

If I have a mortgage, do I need separate mortgage protection or is regular term life enough?

Regular term life can absolutely cover your mortgage. Mortgage protection is just term life sized and structured around the loan. The main difference is whether you want a decreasing benefit that tracks your loan balance (sometimes cheaper) or level term that covers the mortgage plus other needs. We'll compare both and you can decide what fits.

Ready to Compare Your Options?

Get a personalized quote in minutes, or call to talk through your situation. No pressure, just clear answers.

Call Get Your Free Quote